Pension administration software for insurers, pension funds, and scheme administrators

Pension administration software runs the whole scheme: employers and members, contributions in, funds and member accounts, and benefits out. DICEUS Group Insurance Management Platform for Life & Pensions administers pension and group life schemes in one system, covering defined benefits, contribution, hybrid plans, group term life, Accidental Death and Dismemberment (AD&D), and long‑term disability.

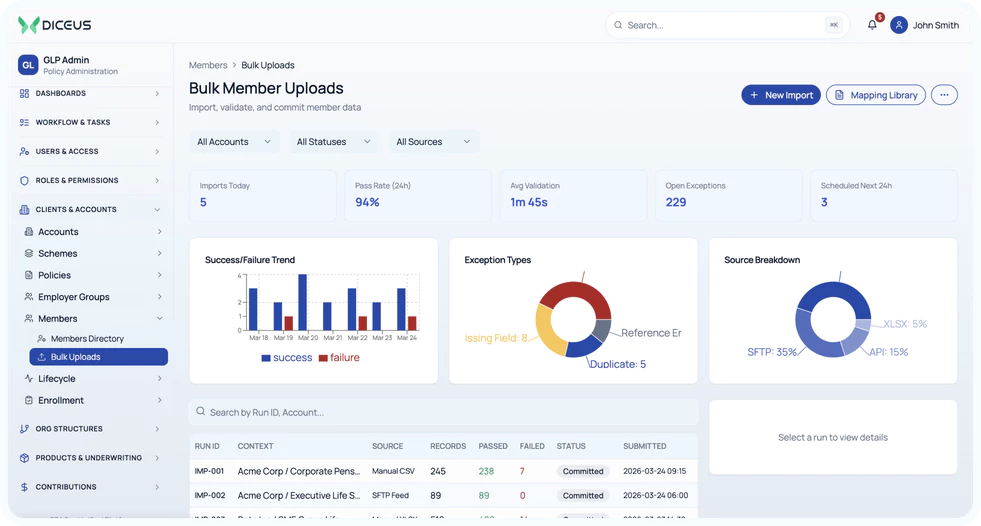
Book a demo Pension administration software bulk member uploads dashboard

What pension administration software does

Pension administration software is the system a pension fund, insurer, or third‑party administrator uses to run its schemes. It holds the employer and scheme, members and their dependents, incoming contributions, the funds those contributions buy, each member’s account, and the benefits paid out at the end. One employer can carry several schemes, each with its own rules, rates, and fund range.

Schemes and members

  • Employer and corporate client accounts
  • Schemes and enrollment parameters
  • Member, dependent, and beneficiary records
  • Bulk data intake with validation

Money in

  • Employer and employee contributions
  • Contribution schedules and adjustments
  • Invoicing, receivables, and collections
  • Reconciliation and general ledger posting

Funds and money out

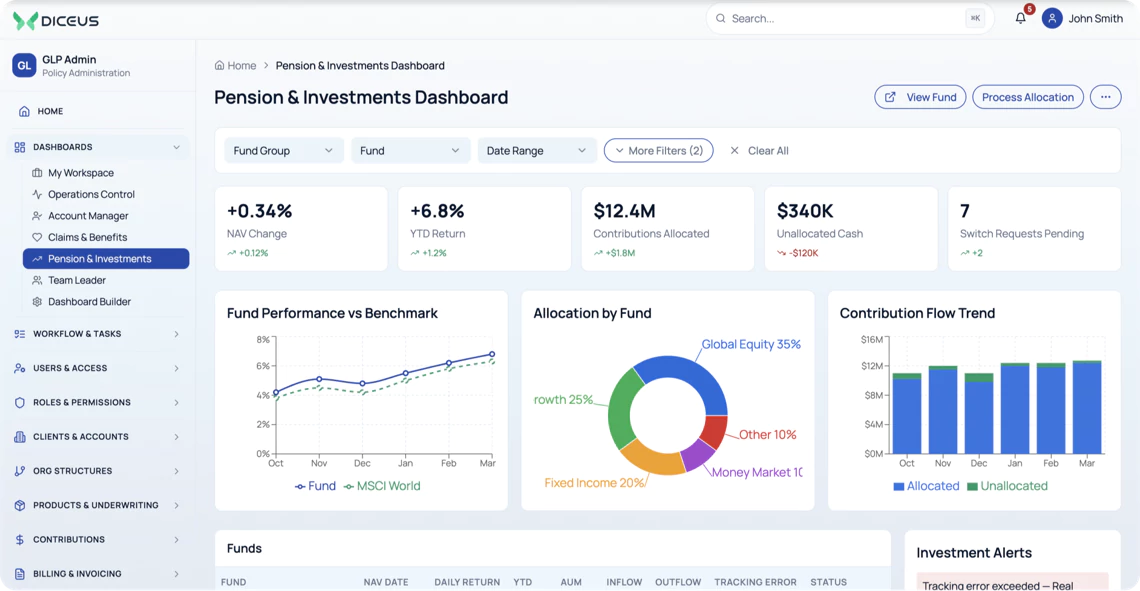
  • Fund setup and performance tracking
  • Scheme and member fund allocation
  • Pension account balances and valuation
  • Life claims and benefit payouts
Pension and investments dashboard

Who it is for

Schemes, employers, and members

A scheme sits inside an employer account, and everything else hangs off that structure. Get it wrong, and every later process inherits the mistake, which is why this is the first thing to look at in a demo.

Clients and schemes

  • Client profiles and accounts
  • Linked schemes and policies
  • Members, contacts, claims, billing
  • Audit and access control
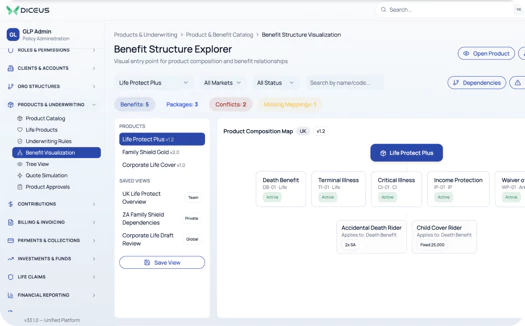
  • Scheme creation and scheme details
  • Enrollment parameters
  • Linked benefits
  • Plan comparison
Benefit structure explorer

Members and dependents

  • Member directory
  • Member onboarding
  • Dependents and beneficiaries
  • Life event changes
  • Member status tracking

Data intake

  • Bulk member upload
  • Field mapping
  • Validation checks
  • Exception handling
  • Create, update, terminate members

Contributions, billing, and collections

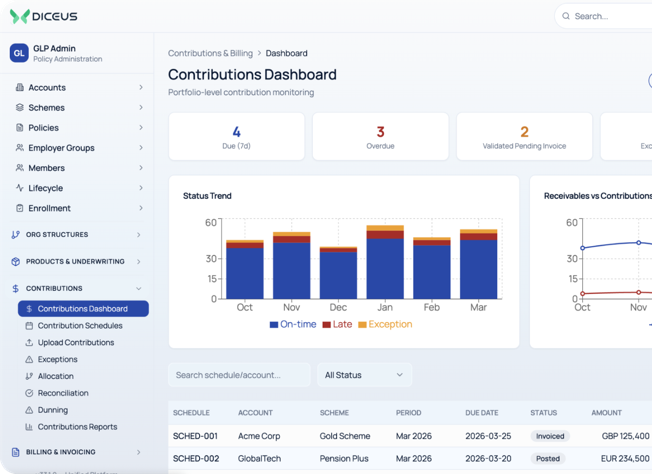
Contributions are where scheme administration is won or lost. Money arrives from the employer on a schedule, must be split between employer and employee portions, allocated to the right members, reconciled against what was invoiced, and posted to the ledger, every cycle, for every scheme.

Contributions

  • Contribution schedules
  • Employer and employee contributions
  • Bulk intake
  • Reconciliation
  • Exception handling

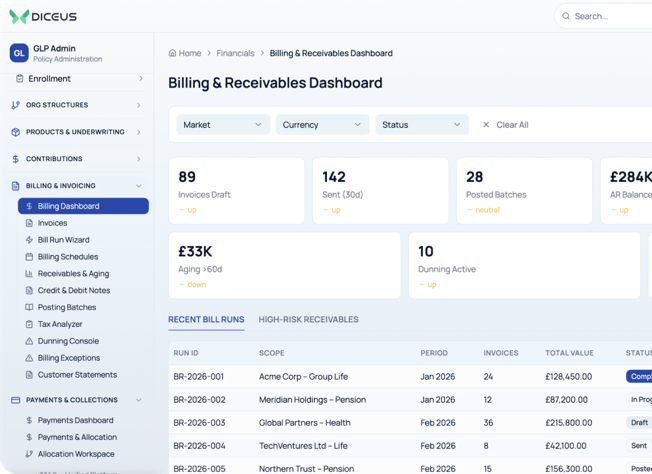
Billing

  • Invoice creation
  • Billing schedules
  • Receivables and aging
  • Dunning actions
  • Posting to the general ledger

Payments and collections

  • Payment tracking
  • Payment allocation
  • Collections status
  • Payment history
  • Reconciliation results
Contributions dashboard Billing and receivables dashboard

Funds, allocation, and pension accounts

This is what a general policy system doesn’t have. Once contributions are collected, they have to buy something; that something has to be valued, and every member has to be able to see their own share of it.

Funds

Provides interfaces for defining and maintaining pension investment funds, their categories, descriptions, and performance indicators.

  • Fund directory and details
  • Fund categories
  • Performance indicators
  • Investment fund management

Allocation

Supports member‑level or scheme‑level allocation of pension contributions into one or more funds.

  • Scheme default allocations
  • Member fund allocations
  • Redirections
  • Balance switches
  • Fund distribution views

Pension accounts

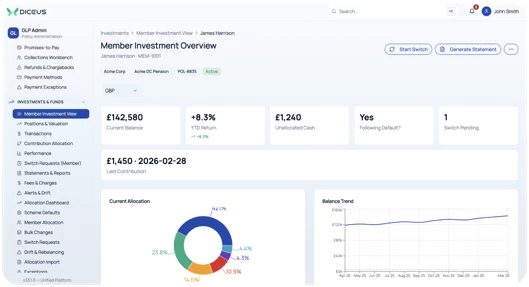
Tracks pension account balances, units, historical movements, valuation records, and account details.

  • Pension account balance
  • Units and holdings
  • Valuation history
  • Transaction ledger
  • Account documents
Member investment overview

Benefits, claims, and payouts

Group life is inside the scheme. A death‑in‑service claim, a disability benefit, and a retirement payout all draw on the same member record, beneficiary data, and documents.

Claims

  • Claims intake and claims review
  • Evidence collection
  • Assessment workflow
  • Claim tracking

Documents and payouts

  • Policy documents
  • Member certificates
  • Renewal packs
  • Batch generation
  • E‑sign and distribution
  • Benefit payout processing against the member account

Self‑service for employers, members, and brokers

Defined benefit, defined contribution, and hybrid

Buyers describe their own scheme by its structure before they describe it by its software. The platform is configured per scheme, so one administrator can run different structures side by side under one employer.

Defined contribution

  • Contributions allocated to member fund accounts
  • Member and scheme‑level investment allocation
  • Account balance and valuation per member

Where this fits against your core system

Two systems get shortlisted for this job and they are not the same thing. This is how to tell which one the situation calls for.

A pension administration platform

  • Contributions, funds, and member accounts are the core of the work
  • Members hold balances that have to be valued and reported
  • Investment allocation and fund switching happen every cycle
  • The scheme, not the policy, is the unit of administration
  • A general policy system has no place to put any of this

Your core policy system

  • Group life is a small line beside a much larger individual book
  • There are no member fund accounts to administer
  • The gaps are in reporting rather than in administration
  • Your policy administration system already handles the group schemes adequately
  • Adding a second system costs more than configuring the one you run

Integrations

Scheme administration sits between the insurer’s core systems, the employer’s payroll, and the fund managers who hold the money. The platform runs beside all three rather than replacing any of them.

Insurer side

  • Core policy and administration systems
  • General ledger and accounting
  • Claims and case systems

Fund and employer side

  • Fund managers and custodians
  • Payroll feeds for contribution data
  • HR systems for member records

Identity and documents

  • SSO and identity providers
  • E‑signature providers
  • Payment and disbursement gateways
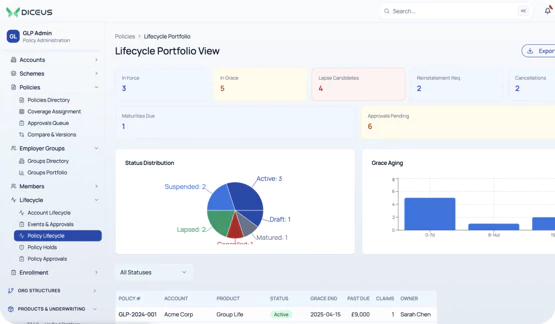
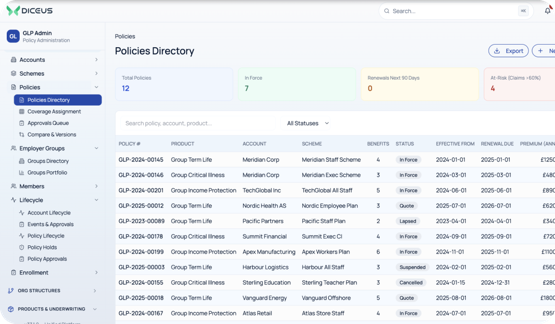
Lifecycle portfolio view Policies directory

Configuration, governance, and compliance

Key benefits for your business

Implementation

  1. Scheme mapping

    We map the schemes as they run today: employers, scheme structures, member classes, fund ranges, and contribution rules. Delivery runs from four weeks to nine months.

  2. Configuration

    Products, scheme parameters, benefit structures, eligibility, workflows, and approval chains are configured in the platform rather than developed.

  3. Migration and integration

    Member records, balances, and transaction history are migrated and reconciled, and connections to the core system, payroll, and the ledger are built.

  4. Go live and handover

    Go‑live runs scheme by scheme rather than all at once, with reconciliation at each step and configuration handover to your own administrators.

Why pension administrators look at this platform

  • Fund allocation, switching, and member accounts, not a pensions tab
  • Client demo available for walkthrough
  • Configuration per scheme rather than development per change
  • Technology partners including Microsoft, Google Cloud, and Oracle
  • Industry partners including VCIA, Swiss Insurtech Hub, Insurtech UK, Claim Technology, Fadata, and InsureMO

Other ready-made software products

See the platform running on a scheme structure like yours

Book a demo

FAQ

What is pension administration software?

Pension administration software is the system a pension fund, insurer, or third‑party administrator uses to run schemes: employer and scheme structures, member and dependent records, contributions, investment allocation, member accounts, and benefit payouts.

What is the difference between pension administration software and a policy administration system?

A policy administration system manages policies. Pension administration software handles schemes and the member accounts within them, including contributions, fund allocation, valuations, and balances. A policy system has no place to store a member’s fund balance, which is why the two are usually run side by side.

Can one platform administer both group life and pension schemes?

Yes. The employer, scheme, member, and beneficiary records are shared, and the difference is what happens to the money: group life pays a benefit on an event, while pension contributions buy fund units that are valued and drawn later.

How are pension contributions reconciled and allocated to member accounts?

The platform takes contribution files in bulk, splits them into employer and employee portions, and allocates them to member accounts according to the scheme’s rules. The platform reconciles allocations against the invoice, handles exceptions separately, and posts the result to the GL.

How does the platform handle fund switching and investment allocation?

Each scheme has a default allocation for new members, and members can hold their own split across one or more funds. Members can redirect future contributions and switch existing balances between funds, with every movement recorded in the transaction ledger.

Can members see their own pension balances?

Yes. The member portal shows the account balance, units and holdings, the funds those contributions bought, and the movements behind the current value. Members can also submit life event and servicing requests there instead of contacting the administrator.

Does DICEUS pension administration software handle life claims and benefit payouts?

Claims intake, document collection, assessment workflow, and claim tracking run against the same member record, and the platform processes benefit payouts against the account. Group term life, accidental death and dismemberment, and long‑term disability are covered within the scheme.

How is the platform configured for a new scheme?

Scheme parameters, benefit structures, eligibility rules, workflows, and approval chains are configured rather than developed, so setting up a new employer or scheme structure is configuration work.

What should a fund look for when replacing a legacy administration system?

Whether member balances and transaction history can be migrated and reconciled, whether scheme changes can be configured without a development request, and whether the system can run scheme by scheme during cutover rather than all at once.

How long does implementation take?

Delivery runs from four weeks to nine months, depending on how many schemes, integrations, and how much member history are in the first release. The timeline is agreed upfront rather than revised as the project goes, and go‑live runs scheme by scheme.
Let’s talk about your project needs

gartner
5/5
6 reviews
clutch
4.9/5
49 reviews

    Contact us

    100% data privacy guarantee

    Thank you!
    Your request has been sent
    We will get back to you as soon as possible

    USA (Headquarters)

    +19293091005 2810 N Church St, Ste 94987, Wilmington, Delaware 19802-4447

    Denmark

    +4566339213 Copenhagen, 2900 Hellerup,
    Tuborg Havnepark 7

    Poland

    +48573568229 ul. Księcia Witolda, nr 49, lok. 15,
    50-202 Wrocław

    Lithuania

    +37069198546 Vilnius, LT-09308, Konstitucijos ave.7
    6th floor

    Faroe Islands

    +298201515 Smærugøta 9A, FO-100 Tórshavn,
    Faroe Islands

    UAE

    +19293091005 Emarat Atrium, 423 Al Wasl Area, Dubai,
    P.O. Box 112344

    Jordan

    +962787500100 Swafeya, Waklat St. 2, Office 302,
    Amman